

SoLo Funds: Lend & Borrow
by Solo Funds
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
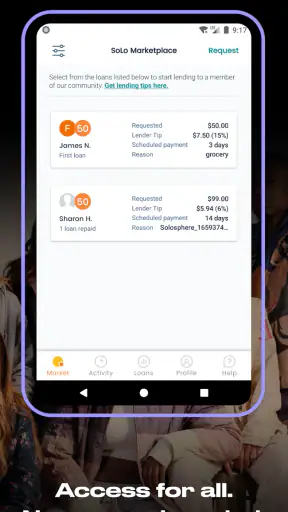
 Analysis by Getfullapps
When an unexpected bill lands before payday, most borrowing options feel heavier than the problem itself. SoLo Funds: Lend & Borrow takes a different approach by connecting people who need short-term help with people willing to lend. I found the idea more personal than a standard finance app, but also less automatic: the experience depends on the request, the people involved, and how carefully you use the tools available.
Developed by Solo Funds, this free finance app is aimed at adults who want an alternative to immediately turning to a conventional loan product. Its basic message is simple: borrowers ask on their own terms, while lenders can participate for potential benefits. That sounds straightforward, yet the important details are in the workflow. This is not an app I would open casually without understanding the repayment responsibility, the timing of a request, and the difference between needing a small bridge and needing a lasting financial solution.
The app has built a sizable audience, with a 4.6 average from around 25 thousand ratings and more than 500 thousand installs. It is rated for Everyone, runs on Android from version 8.0 onward, and the current release is 2.19.0. Those details make it accessible to many phone users, although accessibility should not be confused with suitability. A smooth sign-up process cannot make an unaffordable repayment affordable.
How the everyday borrowing and lending workflow feels
My first impression is that SoLo Funds works best when I treat it as a structured short-term arrangement rather than a general-purpose wallet. A borrower begins with a specific need, considers what can realistically be repaid, and uses the app to present that request. A lender, on the other side, reviews available opportunities and decides whether participating makes sense. The interaction is more deliberate than tapping a button on a traditional credit line.
For a realistic example, imagine a car repair arriving a few days before a paycheck. I would first work out the exact gap, check the date when the money should be available, and avoid asking for more simply because the app allows a request. I would then read every screen carefully before confirming. The useful habit here is to connect the request to a written budget: rent, food, utilities, and existing repayments must come before an optimistic assumption about next week’s income.
That workflow is one of the platform’s strengths. It encourages me to think about why I am borrowing instead of treating credit as invisible spending power. It can be helpful for someone facing a temporary timing problem, especially when the alternative is an overdraft or a rushed decision. On the other hand, it is a poor match for recurring shortages. If the same gap appears every month, another loan only moves the pressure forward.
The lending side requires a different mindset. I would not approach it as a guaranteed return or as a replacement for a diversified savings plan. A lender needs to understand that choosing an opportunity involves judgment and that money committed here is not the same as cash sitting in an instantly accessible account. The app may make participation convenient, but convenience should not remove the need to consider liquidity and personal risk tolerance.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What I would prepare before making a request
I recommend deciding three things before opening the request flow: the smallest amount that solves the problem, the exact repayment date I can support, and the spending category that caused the shortfall. This preparation prevents a common mistake—starting with the amount I wish I had rather than the amount I can responsibly repay.
I would also keep supporting information consistent throughout the process. If the app asks for personal or financial details, accuracy matters more than speed. Rushing through forms can create confusion later, particularly when a request depends on information being reviewed by other participants. A few extra minutes checking names, dates, and amounts is a better shortcut than correcting an avoidable error.
For lenders, my equivalent preparation would be setting a firm personal ceiling before browsing. I would decide how much money can be unavailable without affecting bills or emergency savings. That rule is more useful than making a fresh emotional decision every time an appealing request appears. It also helps separate compassion from financial overextension.
Settings and account habits worth checking
The most valuable “settings” here are the choices that control how I interact with the service, not cosmetic changes. I would review notification preferences so important updates are visible without allowing the app to interrupt every moment of the day. Notifications are useful for time-sensitive activity, but too many can encourage impulsive checking or decisions made without a proper budget review.
I would also check account and security details carefully after installation. A finance app deserves a stronger login routine than a casual game. I would use a unique password, protect the phone itself, and avoid handling sensitive account information on shared devices. These are simple habits, but they matter because the app deals with borrowing and lending relationships rather than merely displaying public information.
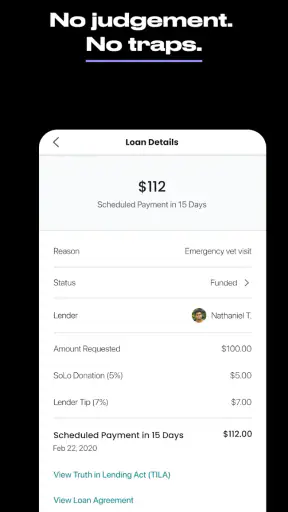
Another practical check is the repayment information attached to a borrowing request. Before confirming, I would reread the amount, timing, and any displayed terms instead of relying on memory from an earlier screen. A concise screen can make a transaction feel simpler than it really is. My rule is to pause whenever a number, date, or condition looks different from what I expected.
Lenders should inspect the information presented for each opportunity and avoid assuming that a familiar-looking request is automatically safe. The app can organize the decision, but it cannot replace a lender’s own limits. I would never use money needed for rent, groceries, taxes, or an emergency reserve. The possibility of a benefit is not a reason to risk essential cash.
These checks also answer a question many new users have: is the app free to download? Yes, it is listed as free, but that does not mean borrowing or lending decisions are consequence-free. I would distinguish the app’s download price from the financial terms and obligations shown inside the service. Those are the details that deserve attention before any confirmation.
Faster patterns that still keep judgment involved
Once the basic process is familiar, I found that speed comes from preparation rather than skipping review. A repeatable borrower routine is especially useful: open the app, identify the precise shortfall, compare it with the next reliable income date, review the request details, and only then submit. Keeping those steps in the same order reduces the chance that urgency will control the decision.
One useful pattern is to keep a small “bridge budget” outside the app. I would record the amount requested, the expected repayment date, and the bills that must be paid before then. This is not a feature I am claiming the app provides; it is a personal system that makes the app safer to use. If the numbers do not fit on paper, they will not become healthier simply because the request is convenient to submit.
For lenders, a repeatable filter works better than browsing without rules. I would decide in advance the maximum amount per opportunity, the total amount I am willing to have committed, and the types of personal circumstances I am comfortable evaluating. The point is not to reduce every decision to a formula. It is to prevent one persuasive request from overriding a limit I set when calm.
Another faster pattern is to separate browsing from committing. I can look at opportunities when I have time, but I would make the final decision only after checking available cash and upcoming expenses. This small delay is valuable because lending can feel rewarding in the moment, while the impact on my own budget appears later. A two-stage habit keeps curiosity from becoming an unplanned financial position.
Borrowers can also use a “minimum viable request” approach. If a smaller amount covers the immediate expense, I would not add a cushion merely because borrowing is available. The trade-off is obvious: a smaller request may solve less if the estimate is wrong, but a larger request creates a bigger repayment obligation. I prefer solving the known problem and keeping the commitment as narrow as possible.
These habits are particularly useful for people who want more control than a conventional credit card provides. A card is often faster at the checkout and may be more familiar, but it can make repayment indefinite if I carry a balance. SoLo Funds feels more intentional because the request is tied to a particular need and arrangement. The disadvantage is that it may be less predictable when I need an immediate, guaranteed payment method.
Where the app is stronger than usual alternatives
I see the clearest advantage in its human, peer-based structure. A traditional lender generally presents a fixed product with standardized rules. SoLo Funds gives borrowers a setting built around requesting help on their own terms and gives lenders a way to choose whether to participate. That can feel more flexible and personal than applying for a conventional loan for a relatively small, short-lived gap.
It may also suit someone who wants to be more conscious of the relationship between borrowing and repayment. The process makes the request visible as an obligation rather than hiding it behind a revolving balance. For a disciplined user, that visibility can encourage better decisions.
Still, a conventional bank account or emergency fund remains better for money I expect to need repeatedly. A credit card may be more suitable for a merchant transaction that requires instant authorization. A regulated long-term loan may be more appropriate when the expense is large and repayment needs a formal schedule. SoLo Funds is not a universal replacement; its value is concentrated in the short-term, specific-need situation.
Advanced limits and the friction I would not ignore
The biggest limitation is psychological: an app can make borrowing feel approachable. That is helpful when the alternative is panic, but dangerous when the underlying budget is already broken. I would skip the service if I needed to borrow for food, rent, or utilities every pay cycle, unless I had a clear plan to change the situation. Repeated short-term borrowing can become a pattern that disguises a larger income or expense problem.
Timing is another consideration. A user who needs certainty at a particular moment should not assume that a peer-based process will feel identical to using cash already in a bank account. Requests, decisions, and repayments involve other people and the terms displayed in the app. I would start early enough to consider alternatives rather than waiting until the last possible hour.
Lenders face their own limit: participation can reduce access to money that may be needed unexpectedly. I would not treat the lending side as a savings account, a guaranteed investment, or a substitute for professional financial advice. Even if the structure is appealing, the correct amount to commit may be zero when my own finances are uncertain.
Privacy deserves a deliberate look as well. Any finance service requires me to think about the information I share, who may see parts of a request, and how I protect access to my account. I would read the app’s current disclosures and permission prompts instead of accepting every screen automatically. That is especially important for users who are uncomfortable with a more personal borrowing experience.
Some people will also dislike the social dimension. If I prefer a completely automated lender, a standard overdraft, or a familiar card, the peer-to-peer format may feel like extra work. The flexibility comes with responsibility: I need to read, choose, monitor, and remember. Users looking for a single tap and no further thought should choose a different financial tool.
Another advanced boundary is separating the app from the quality of every individual outcome. A well-designed workflow cannot guarantee that every request will suit every lender or that every borrower will find the timing ideal. I would judge each transaction independently and keep backup plans for essential expenses. The app is most useful when it is one option in a broader financial plan, not the only option available.
Who should use it, and who should pass
I would recommend trying SoLo Funds to a borrower with a defined, temporary cash-flow gap, a realistic repayment source, and the patience to read each step. It can also appeal to a lender who understands that helping someone and managing personal risk must happen together. In both cases, the user needs to be comfortable making deliberate decisions inside a peer-based financial environment.
I would advise passing if the goal is to finance a lifestyle, cover an ongoing deficit, or obtain a large long-term loan. I would also pass if I could not repay without borrowing again. For lenders, I would pass if the money might be needed soon or if losing access to it would affect essential bills. A free app is not automatically the right tool for a strained budget.
New users often wonder whether the service is suitable for younger family members because the age label says Everyone. I would still treat borrowing and lending as adult financial decisions and make sure the person using it understands the obligations involved. An age classification describes the app’s store rating; it does not replace financial judgment or household rules.
My mastery verdict after building a repeatable routine
After using the workflow as a careful borrower and thinking through the lender perspective, I see SoLo Funds as a focused tool rather than a complete financial safety net. Its best quality is the way it makes a short-term request feel deliberate and personal. Its main weakness is the same feature: because the process feels approachable, users must supply the restraint and planning that the app cannot provide.
The strongest routine is simple but effective. I would define the smallest necessary amount, match repayment to dependable income, review every displayed condition, and keep a separate record of the commitment. As a lender, I would set a total exposure limit, protect emergency cash, and decide independently for each opportunity. These habits make the app faster to use without turning it into an automatic button.
The current version, 2.19.0, supports a product that is already familiar to a broad audience, and the free entry point makes exploring it easy. I would still treat updates as a reason to reread screens and account choices rather than assuming the experience never changes. Finance apps deserve that level of attention because small wording differences can matter more than a polished interface.
My final recommendation is conditional but positive: use it when the need is specific, temporary, and backed by a credible repayment plan. Choose a bank account, emergency fund, card, or formal loan when those options better match the timing, size, or regularity of the expense. The real benefit comes from combining the app with disciplined habits, not from borrowing more easily. For the right user, that balance makes Solo Funds a thoughtful alternative; for someone already trapped in recurring shortfalls, it is a warning sign to seek a broader solution first.
Pros
- Borrowers can request small loans without traditional credit checks.
- The app supports peer-to-peer lending within a community-focused platform.
- Users can build a borrowing history through timely repayments.
- Loan requests and repayment details are managed directly in the app.
- The interface makes it easy to review available lending opportunities.
Cons
- Availability and features may vary depending on your location.
- Borrowers may pay service or instant-transfer fees on some transactions.
- Lenders risk losing money if a borrower fails to repay.
- Some users may experience delays during account verification.
- The platform may require access to personal and financial information.
FAQs for SoLo Funds: Lend & Borrow
What is SoLo Funds: Lend & Borrow, and how does it work?
SoLo Funds is a community-based financial platform designed to let members request short-term money from other members and optionally provide funds to borrowers. Instead of operating like a traditional bank loan, users create requests, review available opportunities, and repay according to the terms shown in the app. Availability, limits, fees, and features can depend on eligibility, location, and current platform policies.
Who can use SoLo Funds, and what are the eligibility requirements?
SoLo Funds is generally intended for eligible adults in supported areas who can verify their identity and connect an accepted payment method. During sign-up, the app may request personal information, identity verification, banking details, and permission to assess account activity or repayment history. Approval is not guaranteed, and eligibility requirements may change, so users should review the current terms before relying on the service.
Does SoLo Funds charge fees or interest on borrowed money?
The cost of using SoLo Funds depends on the specific transaction, the borrower’s selected terms, and the platform’s current pricing model. Some requests may involve optional contributions, service charges, expedited-transfer costs, or other applicable fees rather than conventional interest. Before confirming a request, carefully check the complete repayment amount, due date, and any charges displayed in the app.
Is SoLo Funds safe, and how does it protect my personal information?
SoLo Funds uses account security and identity-verification procedures intended to help protect members and reduce misuse, but no financial application can eliminate every risk. You should download the app only from an official store, use a strong unique password, enable available security features, and avoid sharing login codes. Read the privacy policy to understand how financial and personal data may be collected and used.
What happens if I cannot repay a SoLo Funds request on time?
Missing a repayment deadline can affect your standing on the platform and may result in additional charges, restricted access, collection activity, or other consequences described in the current user agreement. If you expect difficulty repaying, contact SoLo Funds support as soon as possible and review any available options before the due date. Never borrow more than you can realistically repay within the agreed period.

SoLo Funds: Lend & Borrow
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@solofunds.com, visit https://solofunds.com/, or review their https://solofunds.com/privacy.










